It is easy to imagine financial freedom as a finish line reserved for people with huge salaries, flawless budgets, or lucky investment picks. Real life is messier. A car repair appears, grocery prices change, or a month simply costs more than expected.
The useful truth is that a prosperous lifestyle usually grows from repeatable decisions rather than dramatic ones. You do not need to overhaul your life by Monday. You need a few dependable habits that help you keep more of what you earn, use it on what matters, and prepare for both opportunities and surprises.
Direct answer: Financial freedom becomes more achievable when you practice small habits that improve cash flow, build savings, reduce expensive debt, and support long-term investing. Start with the habits that fit your current situation—not an idealized version of it.
What a prosperous lifestyle actually means
Prosperity is not the same thing as looking wealthy. It can mean having enough margin to handle an unexpected bill without panic, taking time off when you need it, helping family within healthy limits, or choosing work because it fits your life rather than because you have no alternatives.
That definition will look different for every household. The common thread is choice: fewer urgent money decisions and more ability to direct your resources toward your priorities.
15 daily habits that can move you toward financial freedom
1. Know your numbers before you judge yourself
Spend two minutes looking at your checking balance, upcoming bills, and recent transactions. This is not about obsessing over every dollar; it is about replacing vague worry with useful information.
A simple starting point is to compare actual spending with take-home pay and include irregular costs—such as insurance, gifts, travel, and repairs—in your plan. The Consumer Financial Protection Bureau recommends reviewing several months of spending so less-frequent expenses are not missed.
2. Give each paycheck a job
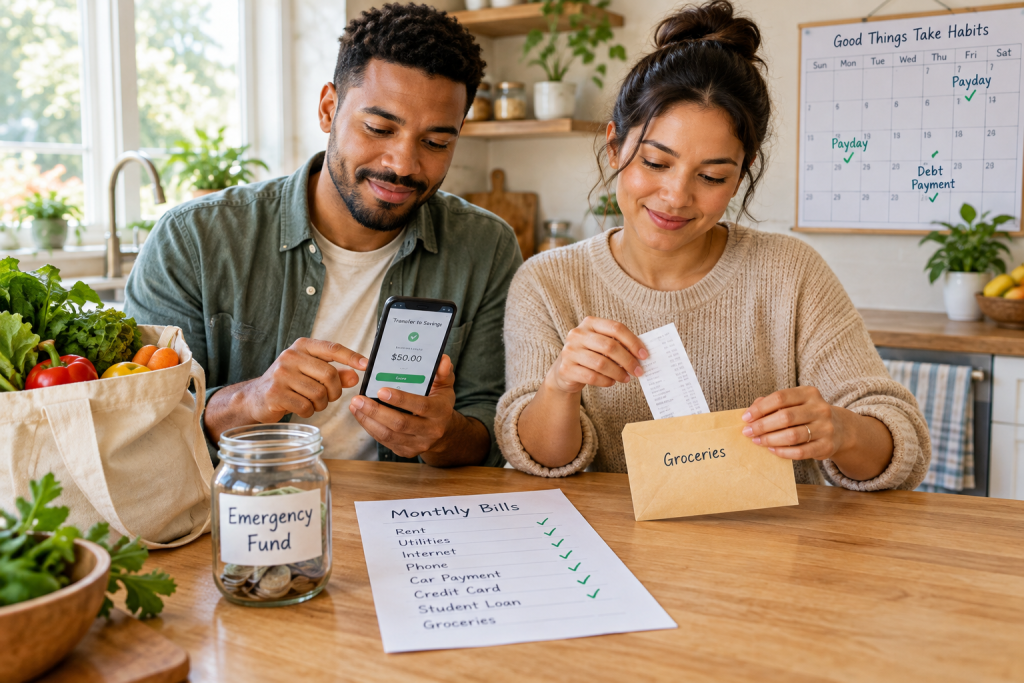
Before money disappears into random purchases, assign it a purpose: essentials, debt payments, savings, investing, giving, and flexible spending. This is often called a spending plan or budget. It is simply a plan for using money on purpose.
Try a short question on payday: What does this money need to do before I am paid again? That question is more practical than chasing a perfect budgeting method.
3. Pause before nonessential purchases
Create a waiting rule that matches the purchase. Maybe it is 24 hours for an online order, three days for a larger purchase, or until the next morning for anything bought when you are tired or stressed.
The pause is not a punishment. It creates space to ask: “Will I still value this next week?” If the answer is yes and it fits your plan, buy it without guilt. Intentional spending is different from never spending.
4. Save automatically, even if the first amount feels small
Set an automatic transfer for just after payday. A modest recurring transfer is often easier to sustain than waiting for a mythical “extra money” month. The amount can grow later.
Automatic transfers can make saving more consistent, but check your checking-account balance so the transfer does not trigger an overdraft fee. The CFPB’s emergency-fund guide also recommends a dedicated goal and a system for regular contributions.
5. Build an emergency fund one layer at a time
An emergency fund is cash set aside for genuine surprises: an urgent repair, an uninsured medical cost, or a loss of income. Start with a small first target, such as one essential bill or $500, then build from there based on your household’s needs and income stability.
For money you may need soon, prioritize safety and access over chasing the highest possible return. Deposits at an FDIC-insured bank are automatically insured to at least $250,000 per depositor, per insured bank, subject to ownership-category rules; investments such as stocks and mutual funds are not FDIC-insured. See the FDIC for coverage details.
6. Make a grocery plan before you are hungry
Food spending can drift because dinner has to happen whether or not you planned for it. Keep a short list of reliable meals, check what you already have, and decide which days are for leftovers or takeout.
This is not about never enjoying restaurants. It is about making convenience a conscious choice rather than the default response to a hectic day.
7. Use a “want list” instead of a shopping cart
When you see something appealing, add it to a note on your phone instead of buying it immediately. Review the list once a week. Many wants fade; the ones that remain can be planned for.
This habit protects your budget without requiring you to pretend you never want nice things.
8. Pay attention to recurring charges
Subscriptions are not automatically bad. Unnoticed subscriptions are. When a recurring charge appears, ask whether you used it enough in the last month and whether it still supports your current priorities.
Canceling one service will not create financial freedom on its own, but recurring costs deserve recurring attention.
9. Pay high-interest debt with a clear plan
Make at least the required payment on every debt by its due date. Then direct extra money toward one target debt, often the balance with the highest interest rate. This approach is commonly called the debt avalanche.
If motivation is the bigger obstacle, paying off the smallest balance first—the debt snowball—can provide a visible win. Either method can work when you stop adding to the balances and keep the plan going. If payments are becoming unmanageable, contact creditors early or seek a qualified nonprofit credit counselor rather than ignoring the problem.
10. Protect your credit by paying on time
Use calendar reminders, autopay for at least the minimum due, or a weekly bill check. On-time payments help prevent late fees and can protect your borrowing options when you actually need credit.
Autopay is helpful only when it is paired with enough money in the linked account. Review payment dates after a job change, move, or shift in pay schedule.
11. Increase your savings rate when income rises
A raise, tax refund, bonus, freelance payment, or paid-off bill creates an opportunity to direct part of the new cash flow toward your next priority. Decide on the percentage before the money arrives.
For example, you might use a raise by putting half toward long-term goals, a quarter toward current needs, and a quarter toward a quality-of-life upgrade. There is no universal split; the habit is to prevent every income increase from quietly becoming permanent spending.
12. Invest consistently for long-term goals
Money needed in the next few years generally calls for a different approach than money intended for retirement decades away. For truly long-term goals, regular investing can put time and compound growth to work—but investments can fall in value, and returns are never guaranteed.
The SEC’s Investor.gov explains that compound growth occurs when returns can earn returns over time. It also notes that all investing involves risk. Use an investment approach that fits your time horizon, financial goals, and ability to tolerate market fluctuations.
13. Diversify instead of chasing the latest winner
Diversification means spreading investments across different holdings rather than betting heavily on a single company, sector, or trend. It cannot eliminate risk or prevent losses, but it can reduce the damage if one investment performs poorly.
The SEC’s diversification guide explains that diversification can occur across asset categories and within them. Broad funds can make diversification easier, though you should still understand what a fund owns and what it costs.
14. Check fees before you commit
Small percentage fees can matter over long periods because they reduce the money that remains invested and able to grow. Before choosing an investment account, fund, or adviser, understand the ongoing fees, transaction costs, and services you receive.
The SEC notes that fees and expenses reduce investment returns, and their effect can compound over time. Read the Investor Bulletin on investment fees before assuming a higher-cost option is better.
15. Do a five-minute end-of-day reset
Close the day by checking one transaction, moving loose change or a small planned amount to savings, packing lunch, or writing tomorrow’s top money task. The action itself can be tiny. What matters is making financial awareness part of normal life rather than an emergency-only activity.
Consistency beats intensity here. Missing a day does not undo your progress; simply return to the next helpful action.
A simple daily money routine to try this week
- Morning: Check your account balance and upcoming bills without judgment.
- Before spending: Use your waiting rule for nonessential purchases.
- At payday: Send a planned amount to savings, debt payoff, or investing automatically.
- Evening: Take five minutes to log spending, plan food, or cancel one unused recurring charge.
If that feels like too much, choose one item. A habit that survives busy weeks is more valuable than an ambitious plan you abandon after three days.
Common mistakes to avoid
- Trying to fix everything at once: Pick the next financial pressure point—late bills, no savings, high-interest debt, or inconsistent spending—and work there first.
- Using investing as an emergency fund: Market investments may be worth less when you need the money. Keep near-term emergency cash accessible.
- Confusing deprivation with progress: A sustainable plan includes some enjoyment and leaves room for real life.
- Comparing your beginning to someone else’s middle: Income, caregiving duties, health, debt, and local costs differ widely. Track your own direction.
The bottom line
A prosperous lifestyle is not built by looking perfect with money. It is built by making the next wise choice often enough that your finances become steadier: know your cash flow, save before spending, use debt carefully, and invest with patience for goals that are far away.
Choose one habit today. Then make it easy enough to repeat tomorrow.
Frequently Asked Questions
What is a prosperous lifestyle?
A prosperous lifestyle combines financial security, personal well-being, healthy relationships, and the freedom to pursue meaningful goals.
How can I achieve financial freedom?
Financial freedom can be achieved by budgeting, reducing debt, investing consistently, increasing income, and practicing smart money habits over time.
What daily habits help build wealth?
Tracking expenses, paying yourself first, investing regularly, reading about personal finance, and avoiding impulse purchases are among the best wealth-building habits.
Does financial freedom require a high income?
No. Many people achieve financial freedom by living below their means, saving regularly, and making intentional financial decisions regardless of income level.
This article is for general educational purposes and is not individualized financial, investment, tax, or legal advice.