By Barry McCoy, Sr. | Updated November 12, 2026
Millions of people work hard, earn a steady income, and still feel financially trapped. The problem is rarely a lack of effort. More often, it’s the absence of a clear financial plan that transforms income into lasting security and freedom.
Learning how to achieve financial freedom starts with creating a practical system for managing money, reducing debt, building savings, and investing consistently over time. The good news is that financial freedom is not reserved for millionaires. It is available to anyone willing to follow that system.
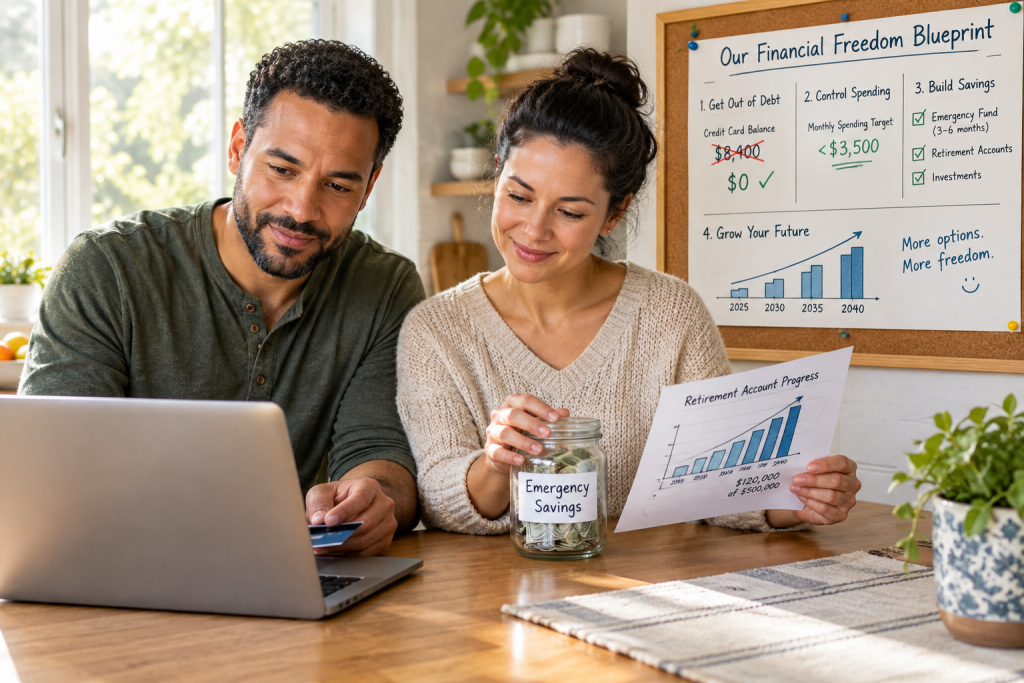
A financial freedom blueprint is not a universal formula or a specific dollar amount. It is a personal roadmap that helps you build enough financial stability and flexibility to make important life choices on your own terms.
Financial Freedom Blueprint at a Glance
1. Define what financial freedom means to you.
2. Understand your current financial position.
3. Create monthly margin between income and expenses.
4. Build an emergency fund.
5. Eliminate high-interest debt.
6. Invest consistently for long-term goals.
7. Increase income strategically.
8. Protect your financial progress.
9. Review and adjust your plan regularly.
There is no guaranteed timeline, investment return, or shortcut. Financial freedom is built through consistent habits repeated over many years.
Important: This article is for educational purposes only and does not constitute financial, tax, legal, or investment advice. Consider consulting qualified professionals before making major financial decisions.
What Financial Freedom Really Means
Many people assume financial freedom means never working again.
For some, that’s true. For others, financial freedom simply means having enough resources to stop living paycheck to paycheck, handle unexpected expenses without panic, or retire comfortably when the time comes.
Over the years, I’ve learned that financial freedom isn’t necessarily about reaching a specific number. It’s about having enough financial margin to make decisions based on what’s best for your life instead of what’s required to survive the next month.
Your version of financial freedom might include:
- Paying off credit card debt
- Building a solid emergency fund
- Leaving a stressful job without fear
- Working part-time by choice
- Retiring comfortably
- Helping children or grandchildren financially
- Traveling without creating debt
“I want enough savings and investments to cover my essential expenses so I can choose how I spend my time.”
That simple statement becomes the foundation of your financial freedom blueprint.
Step 1: Know Where You Stand Financially
Before setting goals, you need to understand your current financial position.
Gather the last two or three months of financial records and identify four key numbers:
1. Monthly Take-Home Income
How much money actually reaches your household each month after taxes and deductions?
2. Essential Expenses
- Housing
- Utilities
- Transportation
- Insurance
- Groceries
- Childcare
- Healthcare costs
- Minimum debt payments
3. Flexible Spending
- Dining out
- Entertainment
- Subscriptions
- Shopping
- Travel
- Hobbies
4. Net Worth
Net Worth = Assets − Liabilities
Your net worth is not a measure of personal value. It is simply a tool for tracking financial progress.
Step 2: Calculate Your Financial Freedom Target
Many online influencers promote a single financial freedom number. Real life is more complex.
Your target depends on:
- Spending habits
- Location
- Taxes
- Lifestyle choices
- Family responsibilities
- Healthcare costs
- Retirement goals
Start with your annual essential expenses.
If your household requires $4,000 per month for necessities:
$4,000 × 12 = $48,000 annually
Then evaluate future income sources such as:
- Retirement accounts
- Social Security benefits
- Pensions
- Rental income
- Business income
- Investment withdrawals
The Financial Freedom Ladder
Level 1: Stability
- Bills are current.
- You are no longer accumulating debt.
Level 2: Resilience
- Emergency savings exist.
- Insurance protection is in place.
Level 3: Flexibility
- Savings or secondary income can support temporary setbacks.
Level 4: Independence
- Income-producing assets support your chosen lifestyle.
Step 3: Create Monthly Margin
The difference between what you earn and what you spend is your monthly margin.
This margin funds:
- Debt repayment
- Emergency savings
- Investing
- Education
- New opportunities
- Future goals
Rather than focusing only on small expenses, review the largest recurring costs first. Housing, transportation, insurance, and food often provide the greatest opportunities for improvement.
A Simple Order for Extra Money
- Keep essential bills current.
- Build a starter emergency fund.
- Pay down high-interest debt.
- Capture any employer retirement match available.
- Expand emergency savings.
- Increase long-term investing.
Step 4: Build an Emergency Fund
An emergency fund prevents life’s surprises from becoming debt.
Examples include:
- Medical expenses
- Vehicle repairs
- Home repairs
- Job loss
- Reduced work hours
If cash is tight, start with a smaller target such as $500 or $1,000. Build gradually toward several months of essential expenses.
Step 5: Eliminate High-Interest Debt
High-interest debt is one of the biggest obstacles to financial freedom because it compounds against you.
Debt Avalanche Method
Focus extra payments on the highest-interest debt first while making minimum payments on all others.
Debt Snowball Method
Focus extra payments on the smallest balance first to create quick wins and momentum.
The best strategy is the one you can consistently follow.
Step 6: Invest for Long-Term Wealth
Once emergency savings and debt management are underway, investing can help you pursue long-term goals.
A sustainable investing strategy often includes:
- Regular contributions
- Diversification
- Low fees
- Long-term thinking
- Avoiding investments you don’t understand
Before investing, ask yourself:
- When will I need this money?
- Can I stay invested through market downturns?
- What fees am I paying?
- Am I diversified?
- Do I fully understand the risks?
Step 7: Increase Income Strategically
Expense reduction has limits. Income growth provides additional opportunities to accelerate progress.
Consider:
- Seeking a raise
- Developing new skills
- Changing employers
- Freelance work
- Consulting
- Starting a small business
A useful strategy is directing a portion of every raise toward financial goals before increasing lifestyle spending.
Step 8: Protect Your Financial Progress
Financial freedom is not only about building wealth. It’s also about protecting what you’ve already built.
- Health insurance
- Life insurance
- Disability coverage
- Auto insurance
- Homeowners or renters insurance
- Beneficiary designations
- Estate planning documents
Step 9: Review Your Blueprint Regularly
Monthly Review
- Review spending.
- Monitor debt balances.
- Verify savings contributions.
- Check upcoming bills.
Annual Review
- Update income and expenses.
- Review net worth.
- Evaluate insurance coverage.
- Assess investments.
- Adjust goals as needed.
A Simple 90-Day Financial Freedom Blueprint
Days 1–7
- Calculate income.
- List debts.
- Review expenses.
- Determine net worth.
Days 8–30
- Create a spending plan.
- Eliminate one unnecessary recurring expense.
- Open an emergency savings account.
Days 31–60
- Automate savings.
- Select a debt payoff strategy.
- Review workplace retirement benefits.
Days 61–90
- Increase one savings contribution.
- Identify one income-growth opportunity.
- Schedule your next financial review.
Common Mistakes That Delay Financial Freedom
- Chasing a universal freedom number.
- Waiting for the perfect time to start.
- Investing emergency savings.
- Ignoring high-interest debt.
- Following unverified financial advice.
- Measuring success only through net worth.
Frequently Asked Questions
How much money do I need for financial freedom?
There is no universal number. The amount depends on your expenses, lifestyle, debt, taxes, healthcare needs, and income sources.
Can I achieve financial freedom on a modest income?
Yes. Consistent saving, spending less than you earn, reducing debt, and investing over time matter regardless of income level.
Should I pay off debt or invest first?
It depends on your interest rates, emergency savings needs, and retirement opportunities. Many people balance both priorities simultaneously.
How long does it take to achieve financial freedom?
There is no universal timeline. Progress depends on income, spending habits, debt levels, savings rates, and investment performance.
Is financial freedom the same as retirement?
No. Financial freedom means having enough resources to make choices about work and life. Some financially free individuals continue working because they enjoy it.
The Bottom Line
Learning how to achieve financial freedom isn’t about discovering a secret shortcut or reaching a magical number.
It’s about building a system that consistently creates more security, flexibility, and choice.
Know your numbers. Create monthly margin. Build emergency savings. Eliminate expensive debt. Invest patiently. Increase income wisely. Protect what you build.
Your financial freedom blueprint does not need to look like anyone else’s. It simply needs to be realistic enough to follow, strong enough to survive setbacks, and flexible enough to support the life you actually want.
Related Reading
- Building Wealth for the Future: Your Path to Financial Prosperity and Positive Wellbeing
- How to Save Money Fast to Pay Bills: A Practical Plan for Today